

Félix Pago - Envíos de dinero
Félix Pago
- 4.4
- 832.00 Reviews
- 100.00K
- Downloads
- Free
- Price
Screenshots
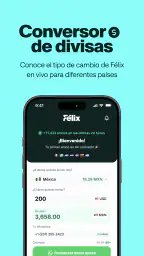
Félix Pago - Envíos de dinero Pros and Cons
Pros
- Fast transfers to supported Latin American countries
- Clear exchange rates shown before confirming a transaction
- Simple onboarding with an intuitive mobile interface
- Transfer tracking helps you monitor payment status
- Useful support options for resolving transaction issues
Cons
- Availability depends on the sender’s and recipient’s country
- Identity verification may take time for some users
- Transfer limits can vary by account and destination
- Fees may differ depending on the funding method
- Recipient access can depend on local banking coverage
 Analysis by All-app
Sending money across borders is one of those tasks that looks simple until the moment you need it to work quickly. I reviewed Félix Pago as a finance app built around transfers from the United States, and my overall impression is that its appeal comes from reducing the number of decisions between “I need to send money” and “the recipient can use it.” That focused purpose makes it easier to understand than a general banking app, but it also means the quality of the experience depends heavily on your phone’s connection, the recipient’s details, and the transfer route available to you.
The app is free to install and is aimed at everyone, which makes the first step approachable for a wide range of users. It comes from Félix Pago, a developer whose product is clearly centered on remittances rather than trying to become an all-purpose financial dashboard. That narrow focus is important: I would consider it when I regularly send money from the United States, not when I want budgeting tools, investment features, bill management, or a complete replacement for my bank.
How the connection affects a money transfer
The most important practical point is that a transfer app is only as comfortable as its connection at the moment you need it. Opening the app, entering recipient information, reviewing the transaction, and receiving confirmation all involve communication with online services. I would not treat Félix Pago as something to depend on in a place where the signal is constantly dropping, especially when the transfer is urgent.
That does not make the app unusual; financial services generally need a live connection to protect account information and process transactions. What matters is how you plan around it. If I were sending money before boarding a bus, leaving work, or entering an area with weak coverage, I would prepare while I still had a reliable connection rather than waiting until the last minute. A few minutes of planning can prevent the frustrating situation of having a completed form but no clear confirmation.
Network quality also affects confidence. With a slow connection, a screen may take longer to update, and that can tempt people to tap the send button repeatedly. I strongly recommend waiting for the app to respond and checking the transaction status before trying again. Duplicate attempts are exactly the kind of avoidable confusion that can arise when someone mistakes a delayed screen for a failed transfer.
For a realistic everyday example, imagine that I am at work and need to help a family member with an unexpected expense. I would first connect to a stable Wi-Fi network or make sure my mobile signal is dependable, open the app, verify the recipient details carefully, and keep the confirmation screen available until I know the action has been accepted. If the connection becomes unreliable halfway through, I would stop rather than start over immediately. That small habit is more valuable than rushing.
Why a focused remittance app can feel simpler
Compared with a traditional bank app, Félix Pago has a more specific job. A bank application may make me move through account menus, domestic transfer options, security prompts, and unrelated financial products before I reach the action I actually want. A dedicated remittance service can feel more direct because the central task is sending money internationally from the United States.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
That simplicity is useful for people who send money to the same family member regularly. Instead of treating every transfer like a new financial project, I can approach it as a repeatable routine: open the service, check the recipient, review the amount and destination, and confirm only when everything matches. The trade-off is that a specialized app may not replace the broader control and record-keeping I expect from my bank.
Compared with cash-based alternatives, the advantage is convenience and a clearer digital trail. I do not need to organize a physical handoff, but I do need a working phone, an internet connection, and accurate information. Compared with other digital remittance services, the deciding factor may be how comfortable I find the particular workflow and whether it suits the people I send money to. I would not choose solely because the app is free to download; I would also examine the final amount, delivery conditions, and any charges shown before confirming a transfer.
Using it in busy mobile situations
Félix Pago makes the most sense for people who manage money from a phone rather than sitting at a desktop. That sounds convenient, but mobile use creates its own risks. A small screen encourages quick taps, crowded surroundings make it easier to overlook a digit, and interruptions can leave me unsure whether I finished the process.
My best practice is to treat the final review as a separate step, not a formality. I would compare the recipient’s name, destination, and amount against the message or note that prompted the transfer. If someone sent me payment instructions through a chat app, I would avoid switching back and forth too quickly; copying an old contact or using a previous conversation without checking it can lead to a mistake.
There is also a privacy angle to mobile use. I would avoid initiating a sensitive transaction while my screen is visible to strangers, particularly on public transport or in a crowded queue. A finance app can be easy to open at exactly the wrong moment. Taking a few seconds to move somewhere private is sensible, even when the transfer itself appears straightforward.
Another useful habit is to keep the phone charged before starting an important transfer. A dead battery is not a connectivity problem in the technical sense, but the result is similar: the process is interrupted and I may lose access to the confirmation details. When the transfer matters, I would complete it before leaving a reliable environment instead of assuming the next location will be equally convenient.
What to do when something goes wrong
The most stressful moment is not usually entering the amount; it is uncertainty after tapping to confirm. The screen may take time to respond, the signal may disappear, or the app may close during a phone interruption. My first response would be to avoid repeating the transaction immediately. I would reopen the app when the connection is stable and look for the current status or transaction record before deciding what to do next.
This is one of the areas where a calm workflow matters more than speed. I would note the amount, recipient, and approximate time before troubleshooting. If I had a confirmation message or reference visible, I would keep it. If the status remained unclear, I would use the app’s available support path and provide those details rather than describing the problem vaguely.
A second practical insight is to separate “the app did not display a result” from “the transfer definitely failed.” Poor connectivity can interrupt the screen without reversing an action that already reached the service. Assuming failure and submitting again is riskier than waiting and checking. I would only retry after confirming that the first attempt was not accepted.
Recipient-side uncertainty deserves the same care. If the person receiving the money says nothing has arrived, I would first confirm the recipient information and the displayed status instead of sending another payment. Timing can be affected by the route used, the recipient’s access, and network conditions. The app is useful for initiating the transaction, but it cannot remove every external dependency involved in receiving funds.
This is also where Félix Pago may not be the right choice for someone who needs extensive financial support tools. If I wanted a full dispute center, detailed account management, or all my domestic and international activity in one banking environment, I might prefer a bank or a larger financial platform. A focused remittance app can make the main action easier while offering less breadth around it.
Keeping mobile data use under control
A money transfer does not usually require the same kind of connection as streaming video, but data-conscious users should still think about when and where they use the app. I would avoid completing an important transfer while my phone is struggling on a congested mobile network. A stable Wi-Fi connection is often more comfortable when available, especially for reviewing confirmation screens or contacting support afterward.
I would not assume that closing the app instantly cancels anything. If I needed to conserve battery or data, I would finish checking the transaction status first. The better approach is to reduce unnecessary retries, avoid repeatedly refreshing a slow screen, and keep the phone connected only long enough to complete the task. Those habits help both with data use and with preventing duplicate actions.
People with limited mobile data should also plan recurring transfers. If I send money on a regular schedule, I would choose a time when I have dependable connectivity rather than waiting until my data allowance is nearly exhausted. I would also keep my phone’s operating system and the app itself in a usable state, since outdated software can make any connection-dependent task more frustrating even when the network is fine.
The current version is 1.1.5, and the app requires Android 7.0 or later. That makes device compatibility worth checking before relying on it for an urgent transfer. Someone using an older phone should test the complete sign-in and transfer flow in advance, while someone with a newer device should still avoid treating compatibility as proof that every network environment will be smooth.
Who will get the most from Félix Pago
I see the strongest fit among people in the United States who send money to family or contacts abroad and want a dedicated mobile route rather than navigating a general bank application. It can also suit users who value a simple, repeatable process and do not want unrelated financial tools competing for attention.
The app has reached over one hundred thousand installs and holds an average rating of 4.4 from around one and a half thousand ratings, with more than eight hundred written reviews. Those figures suggest that it has attracted meaningful use, but they should be read as context rather than a guarantee that every transfer will feel identical. Your experience can still depend on your phone, connection, recipient information, and the specific transaction.
I would be more cautious about recommending it to someone who rarely sends money internationally, dislikes managing financial tasks on a phone, or needs a broad banking relationship in one place. It is also not my first suggestion for a person who expects to work in areas with unreliable connectivity and cannot afford uncertainty. In that situation, a service with a familiar local branch or a bank relationship may be a better backup, even if the digital process is less direct.
Another trade-off concerns comparison shopping. A free app can be convenient, but the download price is not the same thing as the total cost of sending money. Before confirming, I would compare the amount the recipient is expected to receive and any charges or exchange details shown in the transaction flow with the alternatives I already trust. For a small transfer, convenience may matter most; for a larger or frequent transfer, the final value deserves closer attention.
My practical routine for safer, calmer transfers
If I were recommending a routine to a friend, I would begin by saving the recipient information carefully and checking it every time rather than relying blindly on memory. I would start the transfer on a dependable connection, keep the phone charged, and avoid switching between several apps while entering details. I would then pause at the review stage and read the transaction as if I were checking someone else’s work.
After confirming, I would wait for a clear status before closing the app. If the screen stalled, I would record what I had already done and reconnect before taking another action. This approach may feel slower than tapping through quickly, but it reduces the two problems that cause the most avoidable stress: incorrect recipient details and duplicate attempts.
For recurring support, I would also keep a simple personal note of the date, amount, recipient, and confirmation information. That is not a replacement for the app’s own records; it is a practical reference when I need to explain a transfer or compare it with my bank statement. The habit is especially useful when several similar payments are made during the same month.
Finally, I would tell the recipient when I had initiated the transfer, but I would avoid promising an exact arrival moment unless the app clearly shows one. That keeps expectations realistic and gives both sides a shared point of reference if the connection or processing takes longer than expected.
My connectivity verdict
Félix Pago is most convincing when I view it as a focused tool for sending money from the United States, not as a complete financial home. Its free access, Everyone age rating, mobile-first purpose, and straightforward remittance focus make it approachable. The strongest benefit is the possibility of turning an international transfer into a shorter, more understandable routine than the one offered by a general bank app.
At the same time, the experience is tied to the realities of mobile connectivity. I need a reliable connection to begin and verify the transaction, and I need enough patience to check the result before trying again. The app cannot compensate for an incorrect recipient, a dead phone, or a weak signal, so preparation is part of using it well.
My recommendation is positive for people who regularly send money internationally and are comfortable completing financial tasks on a smartphone. I would suggest testing the workflow before an urgent situation, comparing the final transfer value with familiar alternatives, and using the recovery habits above whenever a screen appears stuck. For users who need a full bank ecosystem or dependable in-person help, another option may fit better. For the right mobile remittance user, however, Félix Pago offers a focused way to make a potentially complicated task feel more manageable.
Frequently Asked Questions
What is Félix Pago, and what can I use it for?
Félix Pago is a money-transfer service designed to help users send funds internationally, particularly through convenient messaging-based interactions. Depending on the sender’s country, recipient’s location, and current service availability, it may support transfers to bank accounts, debit cards, or cash-pickup locations. Before sending money, review the available delivery methods, exchange rate, fees, and estimated arrival time shown in the app.
Is Félix Pago safe to use for international money transfers?
Félix Pago uses account verification and transaction-security measures intended to protect users and reduce unauthorized activity. However, no financial service is completely risk-free. You should download the app only from an official store, use a strong password, keep verification codes private, and carefully confirm the recipient’s details before authorizing a transfer. Never send money to someone you do not trust.
How much does Félix Pago charge, and what exchange rate will I receive?
The total cost of a transfer can vary according to the sending country, destination, payment method, transfer amount, and delivery option. Félix Pago generally displays applicable fees, the exchange rate, and the final amount the recipient should receive before you confirm the transaction. Check this summary carefully, because card-provider charges, taxes, or other third-party fees may not always be included.
How long do Félix Pago transfers take to arrive?
Transfer speed depends on the destination, selected delivery method, payment source, verification requirements, weekends, holidays, and the receiving financial institution. Some transactions may be completed quickly, while others can take longer if additional checks are necessary. The app should provide an estimated delivery time and transaction status, but this estimate is not always a guarantee of immediate availability.
What should I do if my Félix Pago transfer is delayed, rejected, or sent incorrectly?
First, open the transaction details and check its current status, recipient information, and any requested verification steps. If the transfer is delayed or rejected, follow the in-app support instructions and keep your confirmation number available. Contact support as soon as possible if you entered incorrect details or suspect fraud. A completed transfer may not be reversible, so verify everything before confirming.


